Friday, November 11, 2011

Veteran’s Day 2011


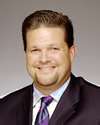
Something to consider as we honor those who have, and continue to, serve our country: it doesn’t matter where you’re from, somebody died so you could enjoy the freedoms that this great democracy is founded upon. I would like to take a moment from my day and from yours to thank our armed forces and all veterans of foreign wars. The picture to the left is of my father who served in the Marine Corps in the 1st Division, Recon from 1967-1969 at a time when not many had a choice but to offer themselves upon the alter of freedom. At a time when the Vietnam conflict was unraveling, we know that all gave some and some gave all. Join me in making every day Veteran’s Day; hold our veterans in your thoughts and in your prayers every day of the year. We must recognize that Freedom is not free. One way to get involved: The Patriot Guard

Reverse Mortgages – Don’t Be Deceived!


The video posted above as well as the title of this post likely led you to think I am going to talk about how costly reverse mortgages are and how there are better options out there. However, you thought wrong.

The above video was the opening to the “Reverse Mortgages vs Traditional Products” NRMLA Annual panel featuring our very own Jeff Birdsell and Joe DeMarkey of MetLife and, in a light-hearted way, shows just how misunderstood reverse mortgages really are. This was a wildly successful session at the conference as Jeff charted fee comparisons, disposable income comparisons and APR comparisons between reverse mortgages and traditional products on a dynamic Excel document. Not only did this tool allow lenders to better understand the differences and similarities between these various products and scenarios, but it provided confirmation that the overall cost of a reverse mortgage is similar to traditional mortgages and, under certain circumstances, can actually be less expensive. In addition, since many large institutions have exited the reverse space, there was a lot of buzz at the show surrounding the smaller players being able to expand their reach and increase their business.

In the end, it’s safe to say that the reverse industry is not to be counted out as a viable industry as we roll into 2012. As long as the smaller lenders capitalize on the void left by the large institutions, success is just around the corner.

Friday, November 4, 2011

Fast Forward: A Sneak Peak into 2012

Tradeshow season has come to a close, and I, for one, am walking into 2012 with an insider look at the direction of the mortgage industry. The MBA Annual hosted in Chicago offered great insight into the trends going into the New Year and particularly what I will be watching. For starters, I noticed a lack of clear direction in the industry as a whole. As everyone slowly digs themselves out from under the collapse, overlooked issues are resurfacing and taking new precedence. Many financial institutions are walking on very thin ice due to their lack of business continuity, and the immense regulations continuously being put in place are still being brushed off. Instead of waiting until you are held accountable, take the competitive advantage and streamline your business processes for increased compliance and reduced risk. This, of course, should not come as a revelation to anyone. It is, however, meant to be taken as a warning. Proceed with caution; do not permit complacency or there will be consequences!

On a more positive note, many other trends leading into the New Year are hopeful signs of things to come. More depository institutions are forming relationships with mortgage companies, forging new business opportunities and ensuring greater strength and growth. In addition, despite signs that correspondent lending is losing steam, the companies that approached me about leveraging the Mortgage Cadence platform for just this purpose at the MBA Annual point in the opposite direction. With many large companies exiting the space, the smaller players are taking advantage of this great opportunity to get in the door and have put correspondent lending back on their radar. Finally, Wall Street is on its way back – with some trepidation, of course. The collapse, coupled with the present media concerns stimulated by the Occupy Wall Street movement, is influencing Wall Street to proceed with caution as they work toward re-establishing mortgage origination channels and relationships. In the end, all of these new developments lead me to believe that we are headed in the right direction going into 2012 and there is great opportunity around the corner. Even if the recession is not over, the mortgage industry is continuing to move more assuredly forward than we have seen in years. Make sure you are on the front of this wave and gain the momentum that will lead to success.

Friday, October 7, 2011

The Return of the Nightmare Implementation

Not so many years ago, the mortgage lending industry was awash with tales of botched integrations and endless (and ultimately fruitless) implementation. It seemed like everyone had their horror stories. When open architectures, Web services and industry-wide data standards started to make it easier for companies to integrate their offerings, we started to see few lending executives running away from new technology solutions.

In the refi boom years, we started to see a number of firms develop good implementation track records, attract strong client bases and serve them fairly well. Those firms that could not earn that reputation lost business or left the business, or both.

But memories in our industry tend to be short and lately we’ve seen a number of institutions fall prey to technology vendors that over promise and then have trouble delivering. Implementations are getting long again and we’re starting to hear more horror stories.

It’s not that mortgage lenders and servicers don’t know how to do due diligence. I think the problem is that institutions are under such pressure to implement solutions that they are falling prey to promises when they should be looking for proven software offered by a company with a solid record of successful implementations. That’s the key to success in our industry--and it always has been.

Photo credit: sticviews.com

Tuesday, October 4, 2011

Fall Conference Season

I hope to see many of you at one of the mortgage industry’s business conferences this fall. After a summer that seemed too short, we’re already back into our suits and heading to shows and expos around the country. In just a couple of week’s our team will be in Chicago for the Mortgage Bankers Association’s 98th Annual Convention and Expo.

Mortgage Cadence will have a booth on the exhibit hall floor, as usual, but this year our new Finale Document Services will also have its own presence there. Spinning Finale off onto its own was a good decision, allowing our marketing team to more easily share the information lenders and servicers are requesting.

I expect this show to be one of the better attended events we’ve seen over the past few years. Many believe, as I do, that the industry is ready to exit the downturn. I expect to be part of many conversations aimed at helping the government step away from out business so that we can do exactly that.

I also expect to see a fair number of new names at this show. Many of the faces are likely to be the same, but mergers and acquisitions are likely to change much of the branding we’ve seen in the past. There will also likely be some new entrants into the business run by entrepreneurs who know that if they can make it during the tough times, they’ll be in great position to profit in the years ahead...if they can last that long.

If you’re planning on being at the show, drop us a line or drop by our booth.

Tuesday, September 20, 2011

Introduction: ELS versus LOS

For more than half a decade I’ve been telling the industry that the future of the mortgage lending business will be built on a new kind of technology. I have argued that the traditional loan origination system (LOS) is an outdated tool that cannot meet the evolving needs of the industry. Over the last year or so, I have seen my predication come true. The days of the Loan Origination System have given way to those of the Enterprise Lending System (ELS), though not everyone understands why or how. Even more peculiar is not everyone even really understands the difference between a LOS and an ELS.

For those who don’t spend their days working to bring mortgage technology to market, this transition may not be as clear. Some still believe that I’ve been talking about a change in labels, but I’m really talking about a change in the entire philosophy of mortgage technology for the loan origination business.

The dust is still settling from the financial crash, but the real requirements for Enterprise Lending Solutions are now clear. We now know what the technology of the future must look like.

From a distance, the LOS of the past and the ELS of the future may appear similar, but upon closer examination the differences become clear. That’s what I plan to do with this series of blog posts. Over the next few weeks, I’ll intersperse posts that compare and contrast LOS with ELS in with my regular blog posts. When I’m done, we’ll have looked at every aspect of modern loan origination technology and the differences between what the industry has used in the past and what it must adopt to compete in the future will become clear.

Anywhere along the line I welcome your comments and questions.

Friday, September 2, 2011

A New Home for Mortgage Cadence

One of the direct results of growth is the required change in facilities to house the people and technology that make a company work. I am very proud of our company’s recent news that Mortgage Cadence’s growth has required such a change. We moved into our new offices over the weekend.

I don’t often talk much about what we’re doing at Cadence in this space, but this was a big move for us and it speaks to changes we’re seeing in the market.

The move only took our company a few blocks from its former location, but miles from where we were in terms of space. Practically doubling the number of FTEs the company employs over the past year was making it very difficult to operate effectively out of the former space. The new offices provide plenty of room to work and expand.

Growing a business during the worst downturn our industry has seen in our lifetimes is definitely something to be proud of and I wish we could take all of the credit. In truth, part of the reason we’ve done so well is because lenders realize that even when times are tough, technology is required to keep their institutions running smoothly. In fact, the right technologies can keep them in business, especially in times like this.

One thing that served us very well was applying our proven origination technology to the problem of default servicing. Servicers found it very difficult to become loan product specialists overnight and they needed technology that could help them operate more like originators, making decisions and underwriting deals in an effort to workout more loans. The technology we developed for the Orchestrator Enterprise Lending System was perfect for this and lenders saw that.

We still have a lot of problem loans to work through and so we expect to continue to grow as the industry recovers. And then, of course, we expect to see the return of the loan originator and a more robust purchase and refinance market.

One thing the new space will provide is more room for people to come together, which will lead to even tighter collaborations between our team and our clients. With a more open floor-plan and plenty of conference and meeting space, we can continue our tradition of coming together in smaller groups to solve the industry’s biggest problems. So we invite you all to come out and see us. You can get all the specifics on where to find us now on our contact page.

In the meantime, we’re gearing up for big industry conferences from both NRMLA and MBA in the months ahead and I hope to see many of you at the shows.